Europe’s biotech M&A market has been on a tear. Since 2023, acquirers from MSD to Novartis to Sanofi have written some of the largest checks in the region’s history — snapping up companies across the UK, Germany, the Netherlands, and Ireland for a combined tens of billions of dollars.
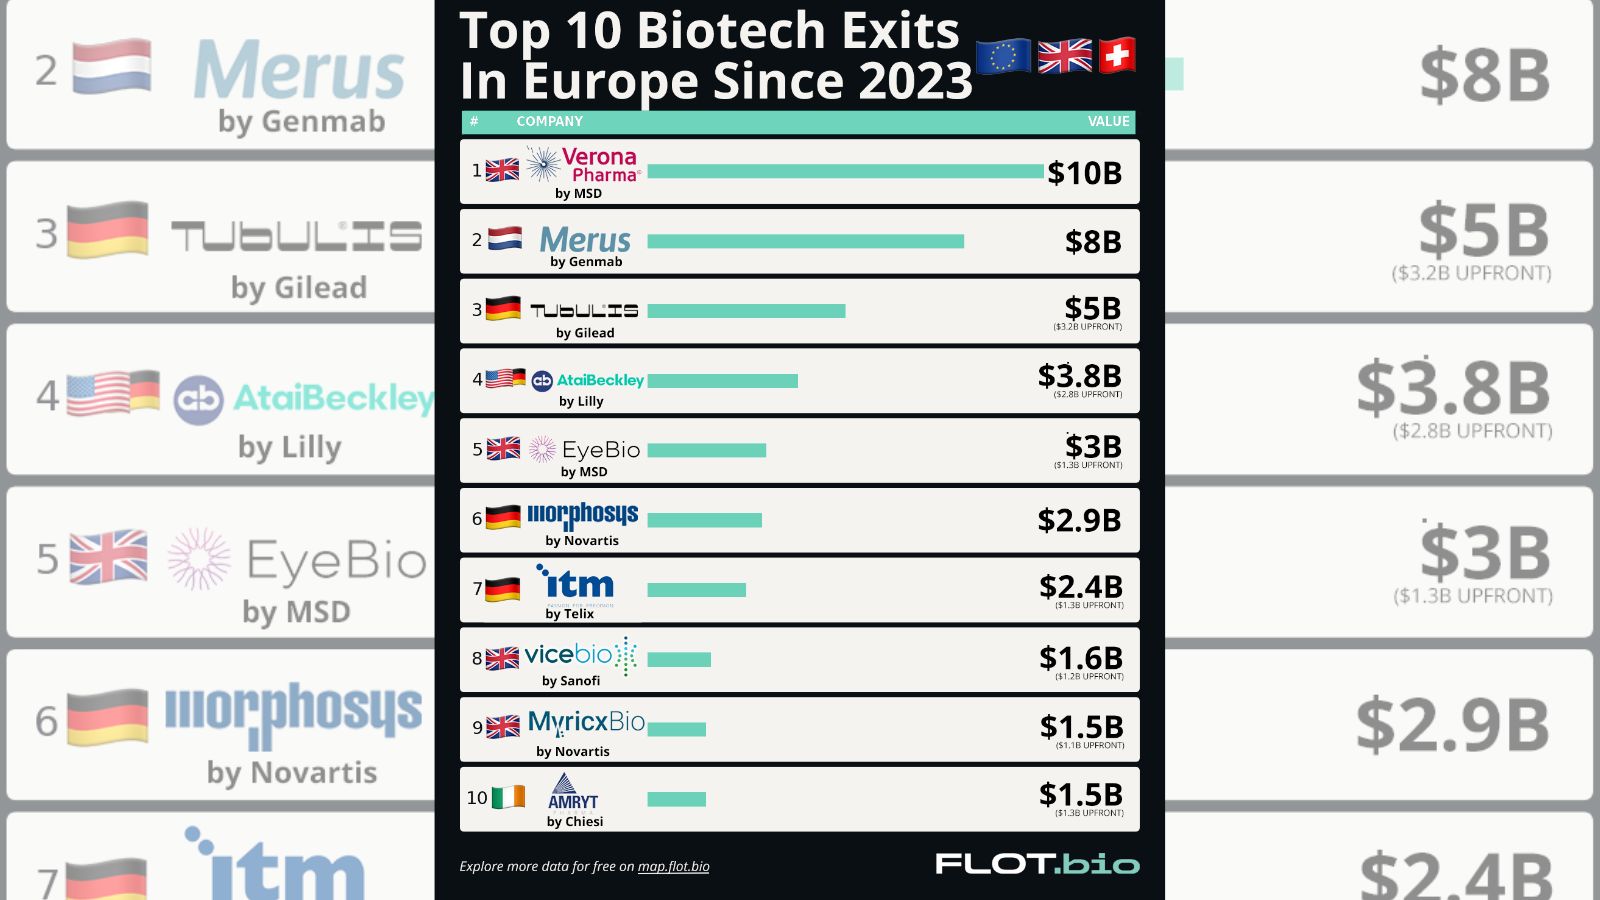
We pulled together the 10 biggest biotech exits in Europe since 2023, ranked by total deal value, using data from Flot.Bio Map. Here’s who sold, who bought, and what they paid.
The Top 10 Biotech Exits in Europe Since 2023
| # | Company | Country | Acquired By | Deal Value | Upfront |
|---|---|---|---|---|---|
| 1 | Verona Pharma | 🇬🇧 UK | MSD | $10B | — |
| 2 | Merus | 🇳🇱 Netherlands | Genmab | $8B | — |
| 3 | Tubulis | 🇩🇪 Germany | Gilead | $5B | $3.2B |
| 4 | AtaiBeckley | 🇺🇸🇩🇪 US/Germany | Lilly | $3.8B | $2.8B |
| 5 | EyeBio | 🇬🇧 UK | MSD | $3B | $1.3B |
| 6 | MorphoSys | 🇩🇪 Germany | Novartis | $2.9B | — |
| 7 | ITM | 🇩🇪 Germany | Telix | $2.4B | $1.3B |
| 8 | ViceBio | 🇬🇧 UK | Sanofi | $1.6B | $1.2B |
| 9 | MyricxBio | 🇬🇧 UK | Novartis | $1.5B | $1.1B |
| 10 | Amryt Pharma | 🇮🇪 Ireland | Chiesi | $1.5B | $1.3B |
Three Trends Behind the Numbers
The UK and Germany are Europe’s exit engines. Four of the ten deals involve UK-headquartered companies (Verona Pharma, EyeBio, ViceBio, MyricxBio) and three involve Germany (Tubulis, MorphoSys, ITM). Together they account for the majority of both deal count and deal value on this list — a signal of where Europe’s most acquirable biotech pipelines are being built.
Big Pharma is paying up for differentiated modalities. MyricxBio, Gilead’s purchase of ADC specialist Tubulis, and Telix’s acquisition of radiopharmaceutical player ITM all point to the same pattern we’ve covered before: ADCs and radiopharmaceuticals have become Big Pharma’s new obsession, and acquirers are willing to pay a premium for companies with a real foothold in those spaces.
Milestone-heavy structures are still the norm. Six of the ten deals split total value into an upfront payment plus milestones — in several cases (Amryt, ViceBio, MyricxBio), the upfront is a high proportion of the headline value, but in others (EyeBio, at $1.3B of $3B, Tubulis, ITM), sellers are taking on real execution risk to get to the full number. Anyone assessing these deals needs to look past the headline figure to what’s actually guaranteed at close.
Why This Matters for Europe’s Biotech Ecosystem
Exits like these are the other half of the story we’ve told about why Europe could have more biotech champions like Argenx: big, well-timed exits are exactly what recycles capital back into the ecosystem, gives investors the returns needed to raise the next fund, and gives founders proof that building in Europe can pay off at a global scale. Ten exits above $1.5B in under three years is a meaningfully different signal than the market was sending a few years ago.
Explore the Full Data
This list is just one slice of what’s tracked on Flot.Bio Map, our free, searchable database of biotech companies across Europe. If you want to go deeper on the companies behind these numbers, a few places to start:
- Free Database of the Top 100 Public Biotechs in Europe
- The 25 Most Valuable Biotech Companies in Europe in 2025
- Top 50 Investors in Biotech in 2026: Europe’s Most Active Life Sciences Funds
Want to explore the underlying company and deal data yourself? Head to map.flot.bio — it’s free.
Deal values are based on publicly disclosed total and upfront figures at announcement and may include contingent milestone payments not guaranteed to be paid. Data via Flot.Bio Map.